Encouraging Pharma in Brazil

The pharmaceutical industry in Brazil grew 12% last year. Are there any indicators suggesting that growth is sustainable? What are the political policies behind this growth?

Brazil confronted hyperinflation from 1965 till 1994.The inflation climbed for three decades, comparable only to what happened in Germany during the 1920s. In June of 1994 alone inflation was 46.58 %. In 1994 the Plano Real (Real Plan) was launched when Itamar Franco was president of Brazil and Fernando Henrique Cardoso was ministry of finance (elected president of Brazil in October that year). Brazil adopted a new currency, the real, but it was recognized internationally only a couple of years later. Inflation dropped in later years but the cost of money to promote technological development in Brazil for many years and even today is the highest in the world.

For almost two decades one could buy public bonds and collect returns of 12% a year. Inflation was still very high, in the range of 6%, and when deducted from these bonds it would assure returns of 6% per year with zero risk. Who could possibly think to invest in technological development instead? In recent years, President Dilma Roussef decided to adopt a series of measures to reverse this trend. Public banks (Banco do Brasil and Caixa Economica Federal) decided to adopt lower tax rates for lending money. Of course private banks had to review their position, which for decades had resulted in the highest profits worldwide.

The common citizen and the small enterprises are now encouraged to obtain loans to promote their business. Interest rates (The Selic Index) are falling. For a long period this index was as high as nearly 20% yearly. Now it is down to 8.5%. That’s still very high, says Dilma Roussef. In the US this rate is close to zero. However when we compare inflation with the new interest rate the difference is gradually dropping, and those that benefited from easy money with zero risk might need to consider alternatives and eventually move in the direction of risk capital.

In truth, though, private risk capital is still scarce. So what is it that has promoted the growth in the pharmaceutical industry? Financing agencies (the Project Financing Agency, also called FINEP, and the National Bank for Social and Economic Development, BNDES) are lending money for technological development, including the pharmaceutical industry, to be paid back in 10 to 15 years, at subsidized interest rates coming in below inflation: 4-4.5 % per year. The loans also include three to five years during which only the interest needs to be paid. This is of course only available to enterprises that can demonstrate assets to back up these so-called reimbursable loans.

When we compare these policies to the series of crisis prevailing in Europe, the US and even countries like Japan, still struggling to recover from natural catastrophes, Brazil emerges as a new potential partner, as I predicted last year. It begs the question, though: where will the intelligence come from to support these pharmaceutical partnerships, should they take place in the coming years? As an answer, Brazil has adopted the most ambitious program in history to train young scientists abroad. Historically, Brazil extends 3000 to 5000 scholarships a year to train students in foreign countries. President Roussef now will fund more than 100,000 scholarships over a four-year period.

However, budgets are not elastic. This investment of billions of US$ dollars will come with sacrifice from other initiatives linked to the Ministry of Science and Technology. The general policy is a clear funding of the private sector and scholarships under government control.

Luiz Antonio Barreto de Castro

Nature Biotechnology’s private biotech feature


The May issue of Nature Biotechnology contains a feature article analyzing the private biotech sector. This is a sister article, of sorts, to the public biotech sector feature we’ve been running for years, and it’s a piece we’ve run in the past.  Like the public biotech article, we’ve made this one free, though for just a month.  You can access it here (PDF is here), and be sure to view the supplementary information that goes along with it.  The article is data heavy, for which we are thankful for Dow Jones/VentureSource for providing the numbers.


Death row for drug development costs estimates?

Last week, FDA Director of CDER, Janet Woodcock, lectured to a full house at the Mission Bay campus of the University of California – San Francisco.  She spoke on ways academic research centers could play a larger role in the development of new medical technologies.  I very much enjoyed the talk, the slides for which are available here.

One aspect of her talk struck me as surprising.  At the start of her presentation, as she set the stage with a description of rising healthcare costs and the significant challenges to developing new medical technologies, she cited the oft-repeated statistic that new drug development requires 10-12 years and costs over $1 billion dollars.  It was a casual remark, not controversial in the least, and since she was stating the obvious, the audience did not so much as blink as she proceeded to the main points of her talk.

I found this a little strange because Dr. Woodcock’s use of the statistic, as I interpreted it, was a tacit acceptance that the numbers are true.  Keep in mind that the FDA is often criticized as being largely responsible for the significant time and expense of new drug development.  Many industry analysts argue that it is due to FDA’s stringent regulatory hurdles that new drug development requires so much time and money.  To what extent this is true is subject to much debate, but I think it’s safe to say that, if I were at the FDA, I might not accept so willingly the magnitude estimates of a problem that I supposedly helped to create.

The numbers are indeed staggering: Ten to twelve years and over $1 billion dollars to develop a new little pill.  Comparisons to “Hollywood economics” and the film industry are often made, but I think oil field exploration is probably more accurate.

These figures were calculated by researchers at the Tufts Center for the Study of Drug Development (TCSDD), an academic think tank focused on the pharmaceutical industry.  The numbers are endorsed by PhRMA, the pharmaceutical industry organization, and they are often used as a justification for the high price tags on new therapies.  How else can a company recoup the significant time and investment in a new product but to charge upwards of $100,000 per year for its use?

These estimates have never sat well with me.  In my opinion, the 10-12 year, $1 billion dollar notion is misleading at best, and flat wrong at worst. Here are two reasons why.

First, these figures are based on historical data.  Specifically, they are based on the R&D expenditures on select new drugs originating in the major pharmaceutical companies, which most recent estimates use data to around 20051.  This is misleading because it measures how much it did cost, not how much it should or could cost.  So, while the bloated infrastructure and wasteful spending of Pharma companies during the boom years of the 1990s and 2000s is widely criticized, those expense measures are accepted as an accurate metric of “true” drug development costs?  Seems strange to me.  If a small town of 50,000 residents has a budget of $10 million, does that mean that it costs $10M to run a small town of 50,000 residents?  Not necessarily. Does it really cost $250 million to execute an inmate on death row in California? Yes, it can, but it doesn’t necessarily cost that much2.

Second, the estimates will go down in the future.  One obvious reason is that Pharma is slashing its R&D budget, so the denominator in the equation is shrinking. Acquisitions and in-licensing have costs too, but not as high as fully-integrated internal R&D and strategic transactions can be structured to mitigate risk (stage of development, option to license, CVRs, ability to terminate, etc.).  Furthermore, drug development strategies, especially clinical trial practices, are trending toward smaller trials in select patient populations with greater use of biomarkers.  These changes appear to reduce both sunk costs (money actually spent on discovery and development) and the cost of failure (which constitutes a substantial of the time and expense estimates), not to mention a positive impact on regulatory and payer reimbursement strategies.

Frankly, NO entrepreneurs or biotech executives today pitch to investors a 10-12 years, $1 billion drug development proposition.  They pitch focused development programs with expedited development timelines and reduced clinical costs.  Moreover, business development teams at the major pharmas similarly balk at licensing opportunities that require extra large and long Phase 3 development programs (think drugs for metabolic disease, with Phase 3 trials enrolling, say, 15,000 patients over 4-5 years and costing $300 million dollars).  I find it hard to see how the 10-12 years, $1 billion metric applies in drug development today.

Drug development is very expensive and lengthy, no doubt, and the TCSDD authors acknowledge the variability across companies and across therapeutic areas.   But my point is that the use of the 10-12 years, $1 billion notion is quickly becoming outdated, if it isn’t already, and is therefore misleading (not to mention self-serving).  So should we expect lower cost innovative drugs in the future?  Maybe, but I don’t expect the costs savings will be quickly or willingly passed on to consumers.  I absolutely believe that the FDA should not lower its safety and efficacy standards, though there is room for updating and validating new clinical endpoints for some diseases. Fortunately, structural changes in how pharma does business in addition to advances in translational medicine means they won’t have to.

Feel free to place your comments below.

Adam Bristol


References:

1)       Kaitlin, K.I. Deconstructing the Drug Development Process: The New Face of Innovation. Nature: Clinical pharmacology & Therapeutics, 87, 356-361.

2)       Tempest, Rone, “Death Row Often Means a Long Life”, Los Angeles Times, March 6, 2005

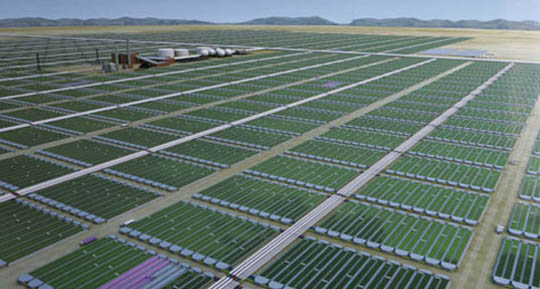
The Green Gold Rush

(Source: dasolar.com)

Investors, companies, governments and scientists around the world have invested significant resources to create a next generation biofuel that reduces dependencies on fossil fuel, opens up new business opportunities and helps protect the environment. While the early generations of biofuels needed agriculture (e.g. sugar cane) and thus competed with food and feed, next-generation microalgae do not require arable land or freshwater to grow and thus do not compete with food crops. They also produce higher yields of oil per hectare of land, produce a higher-quality fuel product and can produce non-fuel high-value products (HVP), such as biopolymers, proteins, animal feed (Spolaore et al., 2006, Waltz 2009). If technological processes can be developed, the potential benefits of engineered algae include the production on non-arable land of biodiesel, methane, butanol, ethanol, aviation fuel, and hydrogen using waste or saline water as well as CO2 from industrial or atmospheric sources.

This promising outlook led to a number of government subsidies and regulatory changes favouring the production of algae biofuels in the US and Europe.[1] Seen as a kind of green gold, a number of companies rushed in to claim their stakes.

Company Capital investment (US$, millions)
Aurora Biofuels (now Aurora Algae) 25+
Algenol 70+
Sapphire Energy 300
Solarvest BioEnergy Publicly traded on the TSX Venture Exchange
Solazyme 70+
Synthetic Genomics 300+

Continue reading →

Will work for cash

Three years ago, at the 3rd Plant-Based Vaccines & Antibodies meeting in Verona , I proposed what I thought was a novel idea to move the field of “pharming” forward.  With Andres Wigdorovitz from Buenos Aires in Argentina, I suggested that companies in the USA and Europe could advance their recombinant plant-produced biologicals product development very significantly by investing in research groups in countries like Argentina and South Africa, where the science was essentially on par with northern countries, but personnel and facilities cost far less.  Moreover, the regulatory and ethical frameworks are often as sophisticated as those of developed countries, and according to the most recent annual report of the International Service for the Acquisition of Agribiotech Applications (ISAAA), in fact developing countries are among the leading proponents of the use of GM plants.

Seriously: of the ten countries growing more than 1 million hectares of GM crops in 2011, seven are developing nations – and six of the ten are in the Americas, with Brazil second to the USA, followed by Argentina, India and Canada.  South Africa comes in ninth, ahead of Australia at 12.

Continue reading →

New Bioentrepreneur article

We’ve posted a new article on the Bioentrepreneur home page, investigating the costs of going public for small companies. You can access both the HTML and PDF versions here.  The author is Mark Kessel, who writes for Nature Biotechnology on occasion, including here (on Sarbanes-Oxley) and here (pharma’s troubled business model).  He’s also hosted one of our Bioentrepreneur “Meet the Author” discussions, which you can find here.


How VCs build companies today

We published in the December issue of Nature Biotechnology a news analysis detailing some of the funding models being used by today’s life science investors. Some are looking to expand syndicates, ensuring that funding is there for follow-on rounds. One is sometimes providing huge A rounds by itself. And though many favor an “asset-based” approach, the R&D platform engine is not as dead as might be thought.

We’ve removed the article from behind our pay firewall, and you can read it here for the next month.  It should be informative to the Trade Secrets audience.

Brady Huggett

Assessing VC funding in biotech

Ever since Prospect Ventures handed back $150M of committed money to its limited partners, there has been plenty written on the lack of venture capital funding for the life sciences.

However, a deeper dive provides a better picture. Bruce Booth has done the diving, and he wrote a blog post about it.

His findings are similar to what we found when digging up research for a news analysis, scheduled for publication in the December issue of Nature Biotechnology. That piece looks at new funding models for today’s startups, and I’ll get it removed from behind our firewall and post a link on the blog next week, after embargo lifts. Until then, you can read Bruce Booth’s piece here.

Brady Huggett

Blue Sky funding

blue.jpg

I read an article in The Scientist funding with a little cynical laugh the other day. It described how “The success rate of the government agency’s grant applications has hit an all-time low” – of 17.4% of all applications. That’s just under one in five: consider, then, that a recent call by South Africa’s National Research Foundation for 40 prestigious Research Chairs in local universities was over-subscribed by at least 10 to 1 – and that was with pre-screening by the institutions. Another call for “blue sky” projects for rated researchers – open to all 2,300-odd such people – was for a total of R15 million a year, and was expected to cater for about 30 projects. Even if only half of all eligible folk apply, that means only 2.5% – 1 in 40 – will receive anything. A further wry smile could be elicited by the fact that the R0.5 million a year (~US$70,000) they will get is significantly less than the US$100 000 that junior NIH grant recipients can expect, and after all that competition too!

In truth, funding for pure science in South Africa is simply bad. My colleague Blessed Okole, who works for a government-funded funding agency in South Africa who is a Trade Secrets contributor, may argue with me – but then, his agency (the Technology Innovation Agency, TIA) funds applied research – and mainly towards the business end of the pipeline, at that.

The NRF should be funding pure science, but their money seems to be tied up in a mixture of ring-fenced initiatives that leaves very little room for any “blue sky” initiatives. In spite of the fact that they had an initiative labeled “Blue Skies”, which raised a large amount of controversy due to the very strange conditions associated with it, which a response by the NRF President in South Africa’s premier science journal did nothing to quell. As it was, in 2010 the breakdown of the NRF’s funding was as follows:

Broad Investment Areas (% of budget)

  • Established Researchers (18%)
  • Human Capital Development and Unrated researchers (23%)
  • Strategic knowledge Fields (23%)
  • Strategic Platforms (Including at the National Research Facilities) (11%)
  • International initiatives (11%)
  • Applied & Industrial Research & Innovation (14%)
  • Community Engagement Research (0.2%)

TOTAL (100%)

Thus, less than one-fifth of their disbursement budget of around R300 million (~US$40 million) goes to established researchers – the 2300 people rated A to C – and then very little of that goes to “free” or curiosity-driven projects.

The fact that we get any funding at all, in the context of being scientists in a developing nation in Africa, is probably something to praise. However, however…the government, through the national Department of Science & Technology recently lavished R1 billion on a pilot project called the Karoo Array Telescope, which is aimed at proving to the world that South Africa can host the Square Kilometre Array. They also spent at least US$1.8 billion in failing to develop the now-defunct Pebble Bed Modular Reactor project, and the now infamous “Arms Deal” will have cost over US$10 billion by the time it has finished.

So it is not because we have no money, that there is not very much money for science – it’s just that the government doesn’t seem very interested. So it goes…we just play the lottery – pardon, the NRF funding game – with the rest of the country, and meanwhile we try to get money in from outside the country just as hard as we can. Who knows, maybe TIA can deliver – and maybe porcines will be airborne soon. We live in hope!

Ed Rybicki

The Moneyball VCs

moneyball.jpg

What makes a great venture capitalist? Conventional wisdom says it’s the experience, expertise, Rolodex, and the visionary eye for spotting the Next Big Thing.

But what if this were wrong? What if the important variables in the statistical game of hitting one or two “grand slams” in a VC portfolio, which then make up for the dead or dying companies, could be identified and replicated? Why can’t there be a Moneyball moment for the VC industry?

Enter Correlation Ventures and Ulu Ventures, two new firms with heavy emphases on ‘quant’ approaches. Launched in stealth mode in 2010 with limited partners including University of Texas Investment Management Company and others, Correlation’s co-founders David Coats and Trevor Kienzle spent years building a proprietary database of company data and outcomes from which to mine for variables critical to success. This was not trivial; data on private companies is just that, private, and Messrs. Coats and Kienzle forged relationships with Dow Jones and multiple VC firms to access historical non-public data. For hundreds of historical deals, they catalogued over 50 variables, such as syndicate composition, management experience, and, most importantly, outcomes metrics for those investments. Correlation could then run multiple regression analyses and identify those variables that account for the most variance. Now in the business in making new investments, Correlation is able to conduct due diligence quickly – typically within two weeks – by entering relevant inputs into their model and adhering to a strict threshold on overall profile before doing deals. They expect to invest in 50 to 75 companies with the average investment size between $1 million and $4 million.

“There is a pervasive notion [in venture capital] that the best investors are intuitive pattern matchers with an uncanny ability to spot new market opportunities,” says Clint Korver, partner at Ulu Ventures in Palo Alto. Korver and co-founder Miriam Rivera believe that quantitative analysis can enhance experience by allowing intuition to be intelligently applied to investment decision making. Unlike Correlation, Ulu takes a Bayesian approach, explicitly incorporating expert judgment about the future into their models. Ulu first builds a map of the key drivers of risk and value for a startup, including factors such as life stage risks, total addressable market, margins, competition, exit multiples, and future capital needs. Ulu then combines intuition and data to assess possible ranges and probabilities for each of uncertainty. A cash flow model ties it all together, allowing Ulu to perform sensitivity analysis and focus due diligence on the risks that matter most. Korver says “while we look for companies with probability weighted multiple on investment of 10x or better, we do not blindly follow the numbers. We make decisions based on a compelling story.”

There are several intriguing elements in the new “quant VC” development. First, we would argue that an important aspect of what VCs mean by “experience” is indeed being an expert pattern matcher – quickly identifying pitfalls and seeing the ingredients for success. A strict quant approach like Correlation’s is essentially the same thing, but with the added benefit of removing cognitive biases and prejudices and, importantly, discovering relationships between variables and outcomes heretofore unrecognized.

Second, our hunch is that the general applicability of the approach varies depending on the sector. One obvious challenge is that quantitative approaches to investing, be them in public or private markets, are necessarily backward-looking in that they use historical data, and there can be no guarantees that the future will replicate the past. We see this challenge as most relevant to sectors undergoing significant dislocation, such as healthcare, in which legislative reform and widespread restructuring is redefining value drivers in the industry. Similarly, it is unclear how quantitative metrics can inform investment decisions in de novo fields such as renewable energy or nanotechnology with no historical precedent. Another point to consider is the extraordinary holding times now required for VC-backed healthcare investments – more than five years from seed investment to exit, according to recent data from Silicon Valley Bank.

But those data are restricted to companies that actually had an exit; many, many more are held much longer. Ten years seems like a lifetime in a high technology industry, and to compress that period into inputs and outputs seems ripe for misattribution.

By contrast, IT and software industries have a rich investment history dating back to the birth of the VC industry with multiple business cycles and thousands of data points. IT businesses, in particular, are largely driven by market forces as opposed to scientific hypotheses, which also make them easier to model. The time to market is also significantly shorter. Groupon, which recently completed a $700M IPO, was founded in 2008, just four years ago – that’s value creation at breakneck speed. Consider these advantages in light of recent data published by partners at Atlas Ventures and Highland Capital suggesting that IT investments exhibit significantly higher variability in their return multiples compared to life sciences investments.

With 100x outliers, such as Facebook and Zynga, the larger variance may lend itself to delineating key factors for success in IT investments. Not surprisingly, tech-orientated VCs including Google Ventures are beginning to embrace quantitative approaches to uncover lessons and refine their investing approach.

We’re attracted to the data-driven nature of the quant approach, and how Correlation makes and monitors investments is certainly more sophisticated that we can appreciate. But the jury is still out in whether venture-like returns will follow, especially in industries with high capital costs and long product development times, such as life sciences and healthcare. That said, with the venture capital industry contracting as a result of poor historical returns, quantitative venture capital offers an innovative approach for limited partners to mitigate risk and systematize early-stage investing with lean investment teams. Perhaps the rise of quantitative VCs also reflects the maturity of the industry, now with 30 years of ample historical data and the necessary informatics technology to digest it.

Innovative investing styles should be just as welcomed as innovative technology in the VC industry.

Adam Bristol and Justin Chakma